This is a sponsored post.
After miserably failing my first attempt at my practical driving test at the beginning of August, I’m thrilled to have secured a cancellation slot for a second attempt next Tuesday!
I couldn’t have been more ready to sit my test last month, having waited over a year to give it a go due to the DVSA driving test backlog caused by various lockdowns. Sadly, nerves let me down, but I’m feeling much calmer about my upcoming attempt.
I’ve held back on buying a car until now, as I wasn’t sure how long it’d be before I got on the road. Now, though, I’m finally starting to search for the perfect car. As I’ve opted to learn in an automatic car, I’ve limited my choices when it comes to the range of second-hand cars available within my budget. However, I’ve got my heart set on a MINI Cooper for my first car.
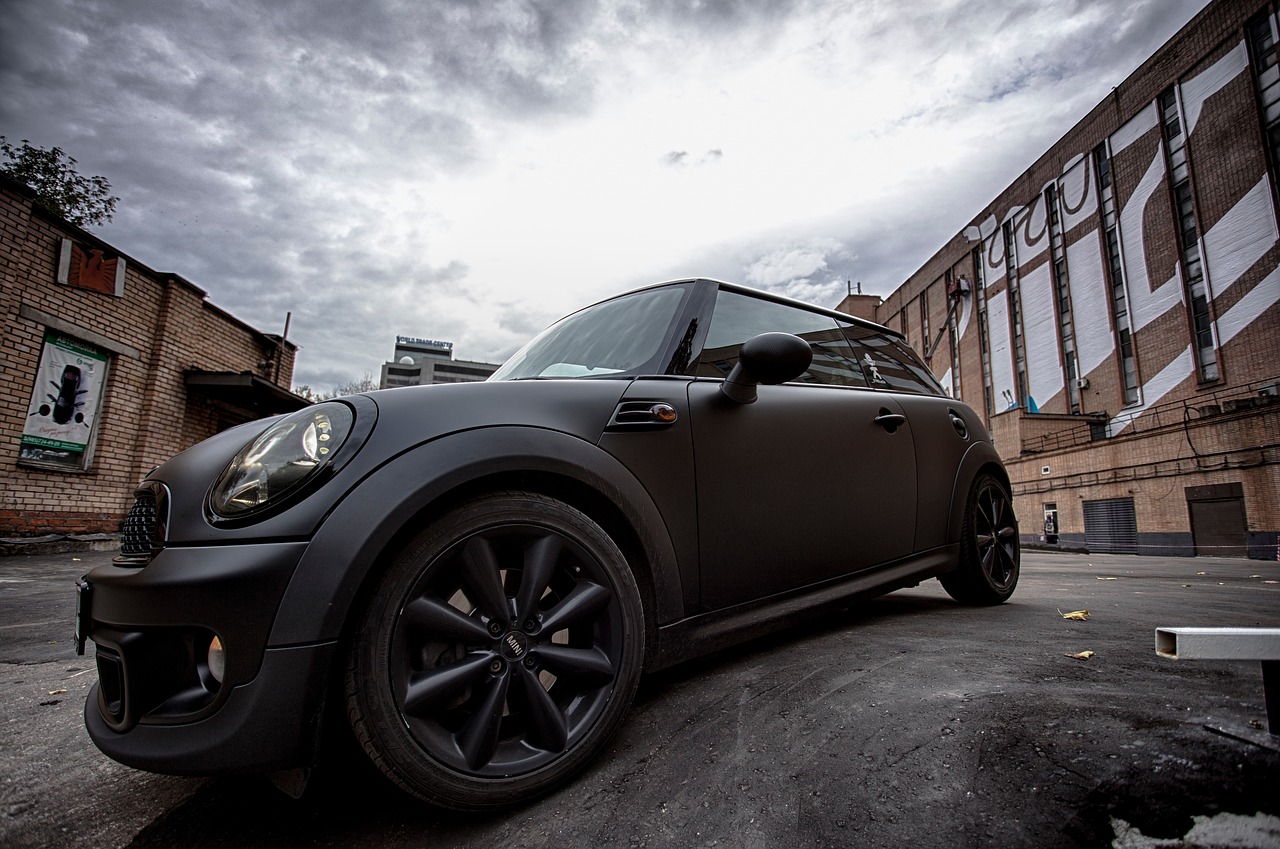
As second-hand automatic MINI Coopers can be hard to come by, some friends have suggested I explore car financing. While this idea doesn’t appeal to me personally as I’m currently saving to buy my first home, I can certainly understand why some drivers choose to go down this route.
While doing some research into the topic, it became apparent to me just how confusing it can all get, especially for new drivers like myself. So, I thought it might be useful to share some of the key points I took away from this which helped me to decide that, for me anyway, holding out for a decent second-hand MINI is the best course of action to take.
If you’re a new driver like me, here are a few points to think about before you take out any form of car finance. This isn’t an exhaustive list, however; be prepared to do plenty of your own research before finding your dream car.
What new drivers should know about car finance
It’s not an option for 17-year-old drivers
By law, in order to sign a credit agreement, you need to be aged at least 18. This means that car finance simply isn’t an option for 17-year-old new drivers, as they wouldn’t be allowed to sign the financing contract.
However, if you’re a 17-year-old driver keen to take out car finance, you could consider building up your credit score so that it’ll be easier to pass any credit checks once you do turn 18. Even something as simple as adding your name to the electoral roll at your address can have a considerable impact on your rating.
You may be refused finance without a credit history
If you’re a new driver, then there’s a high probability that you might be quite young, perhaps only around the age of 18.
As you may not have taken out any form of credit agreement in the past – such as for a contract mobile phone, credit card or mail order catalogues, for example – you might be surprised to find that you could get declined credit simply for having no borrowing history.
To find out if you have a credit history and what your score is, visit a reputable website like Experian, where you can sign up for a free trial as a new member to check out your credit rating.
If you discover you don’t have any form of credit history, there’s no need to worry. Many lending providers recognise that some people looking to borrow money have never had a credit history before. Rather than assume this means you won’t be able to pay back any money you lend and refusing you credit outright, they may be able to offer you No Credit Car Loans instead.
Even for 18-year-olds, it can be difficult to access
Even once you’ve reached your 18th birthday, car finance can still be incredibly difficult to access.
As securing finance usually means having a secure, regular full-time income and a sound credit history, many 18-year-olds are simply unable to meet the eligibility criteria. The majority will still be studying at school, college or university and at best, may only have a part-time job to support themselves. However, the exception to this will be if you happen to be running your own business and you require a car for work purposes, in which case you can probably cover the costs with a business loan from a designated provider like Loan Corp, if you can be confident you’ll be able to pay it off before the interest starts building up.
While gaining access to car finance can get easier as you get older, it can still be a challenge to get accepted if you’ve got a bad credit score, however.

Making too many applications at once can damage your credit score
When you apply for a car financing quote, the lending provider will carry out what’s known as a ‘soft’ credit check.
If you decide to proceed with the quote and go ahead with the agreement, they’ll then carry out a ‘hard’ credit check. When they carry out this second check, it leaves a note or ‘footprint’ on your credit file. Too many applications in a short period of time could cause other potential lenders to think you might be desperate to borrow money, which may make them less likely to lend to you.
Can you afford the monthly repayments?
Many new drivers turn to car financing as a means of buying their dream car, if they haven’t managed to save up to buy their own car and if they’re not able to access finances through other means, like lending money off parents or other family members, for example.
While this can be a tempting option as it means you’ll be able to get your hands on a flash new car to drive around in, you need to realise that car financing agreements have long-term repercussions.
Dependent on the length of your agreement, you could be making repayments for years to come. Can you afford the monthly repayments now, and would you still be able to afford them if your circumstances changed? What if you were to lose your job? Would you have any savings in place to fall back on? If the answer to these questions is no, or if you’re unsure of what the answer would be, this could be a good indication that car financing isn’t the best option for you.
The interest rates can be high
One of the biggest factors to consider when exploring car financing options is the matter of interest. Interest rates can be extortionate, so it really pays to consider whether you feel comfortable paying the stated interest rate, as it could really bump up your monthly fees.
You should also consider whether the interest rate would increase if you were to default on any of your payments. If so, you need to ask yourself what the likelihood is that you might miss a payment and, if you did, would you be able to afford to continue with the new payment rates with the added interest factored in?
When it comes to car finance for new drivers – or for any kind of driver, for that matter – there really is a lot to consider. Take time to do your research to help you to work out whether it is the best option for you; while it can work out well for some, it’s not a decision that should be taken lightly.
This is a sponsored post.